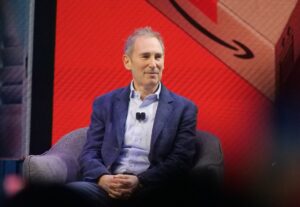
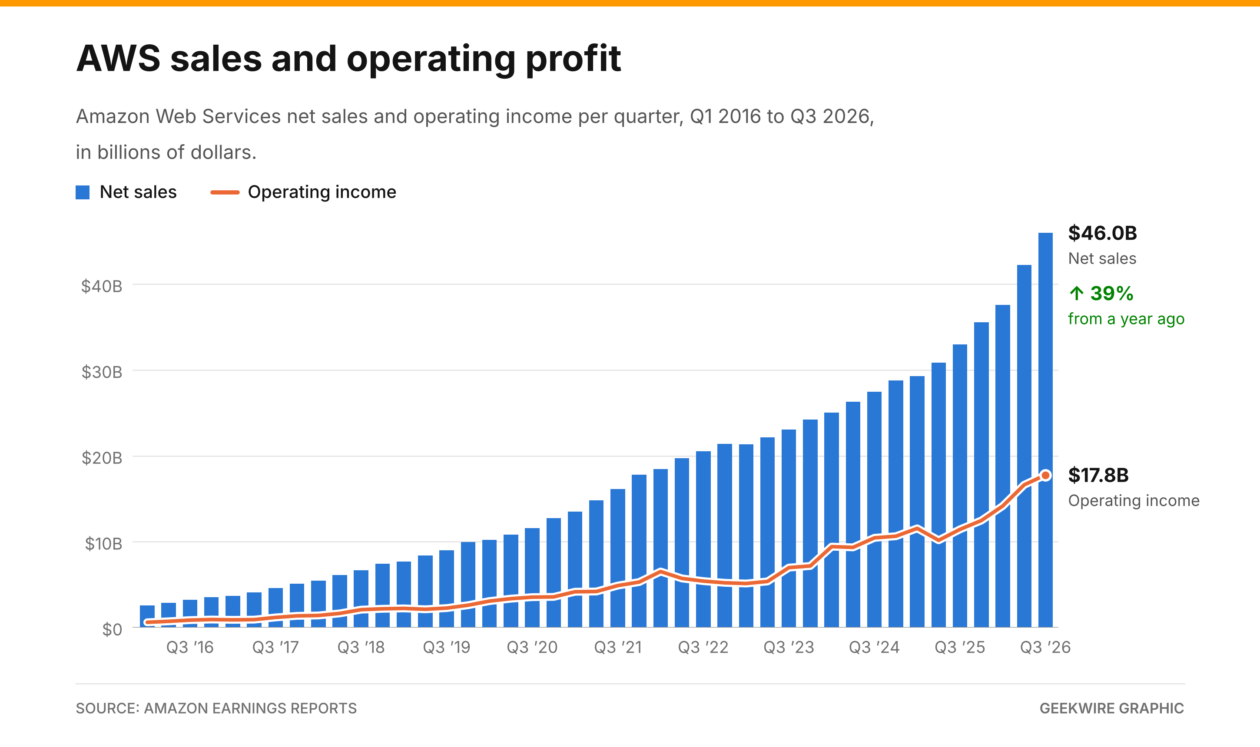
Amazon Web Services revenue grew 39% to $46 billion in the third quarter, its fastest pace in nearly five years, and Amazon CEO Andy Jassy said he expects the cloud unit to top 40% growth in both 2027 and 2028.
That wasn’t enough for investors. Amazon posted earnings of $1.89 per share, well short of the $1.97 analysts expected, as higher interest costs on its growing debt and other losses ate into its profit, even though its operating income beat expectations.
Revenue of $201.9 billion, up 12%, came in just under estimates. Shares fell more than 7% in after-hours trading, after closing down 4% during the regular session.
Update: On the earnings call, Jassy said AWS has a backlog of $578 billion in contracted future revenue, more than double a year earlier. He also said Amazon expects to spend “meaningfully more” on capital projects in 2027 than the roughly $220 billion it plans for this year.
Amazon may need to count on its legendary willingness to be “misunderstood for long periods of time,” as it asks investors to look past the costs to where its biggest businesses are headed.
In the company’s earnings release, Jassy said Amazon’s retail business is gaining market share with improving margins. Retail sales, including online stores, physical stores and third-party seller services, totaled nearly $500 billion over the past 12 months, and AWS is now at a $184 billion annual revenue run rate.
“There has never been a trillion dollar revenue business, and we may have two of them in the next 5-10 years,” he said.
On the earnings call, Jassy said those two businesses are AWS and Amazon’s stores business.
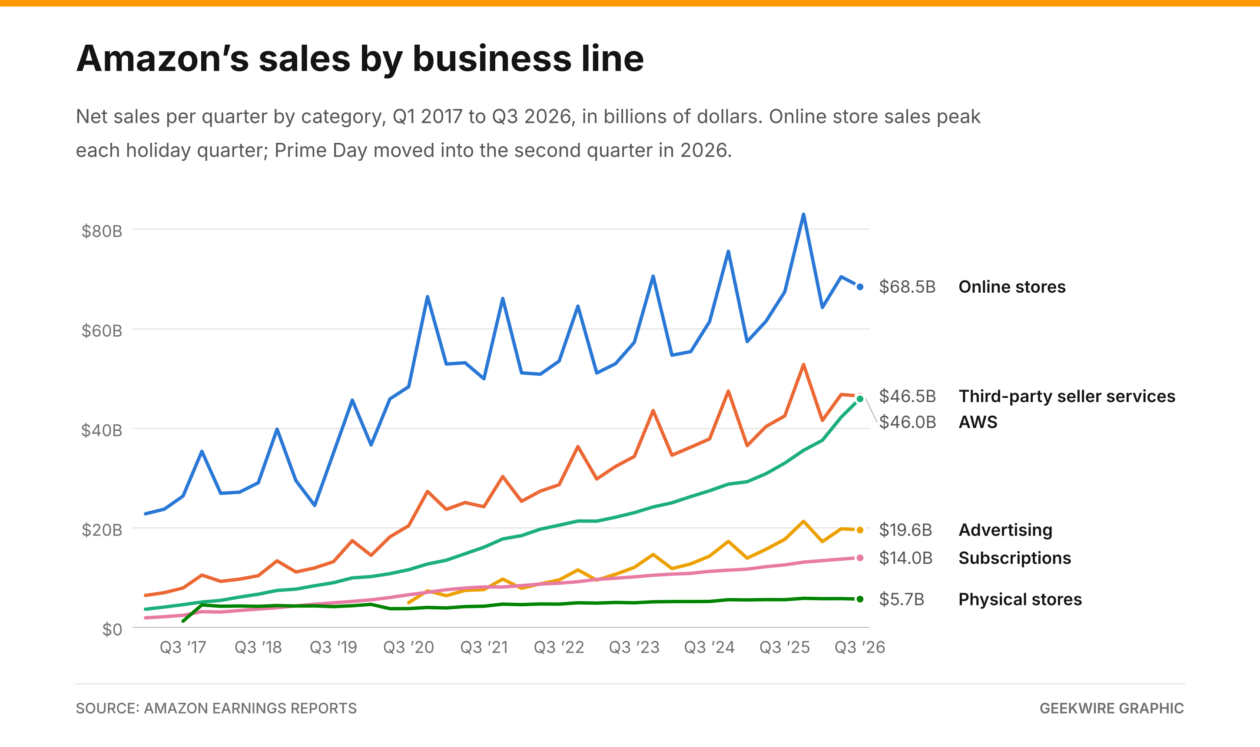
Advertising grew 11% to $19.6 billion, or 12% excluding currency changes, down from 22% on that basis a year earlier. Amazon blamed the timing of Prime Day and a few other factors, and said it expects ad growth to return to the high teens in the fourth quarter.
Online stores grew 2% to $68.5 billion, held back by Prime Day moving into the second quarter this year. Amazon said overall revenue growth would have been about 4 percentage points higher without the shift.
Third-party seller services, the fees Amazon collects from merchants on its site, grew 9% to $46.5 billion. AWS came within about $500 million of it.
Subscription services, which includes Prime memberships, grew 11% to $14 billion.
Physical stores, mostly Whole Foods, grew 2% to $5.7 billion.
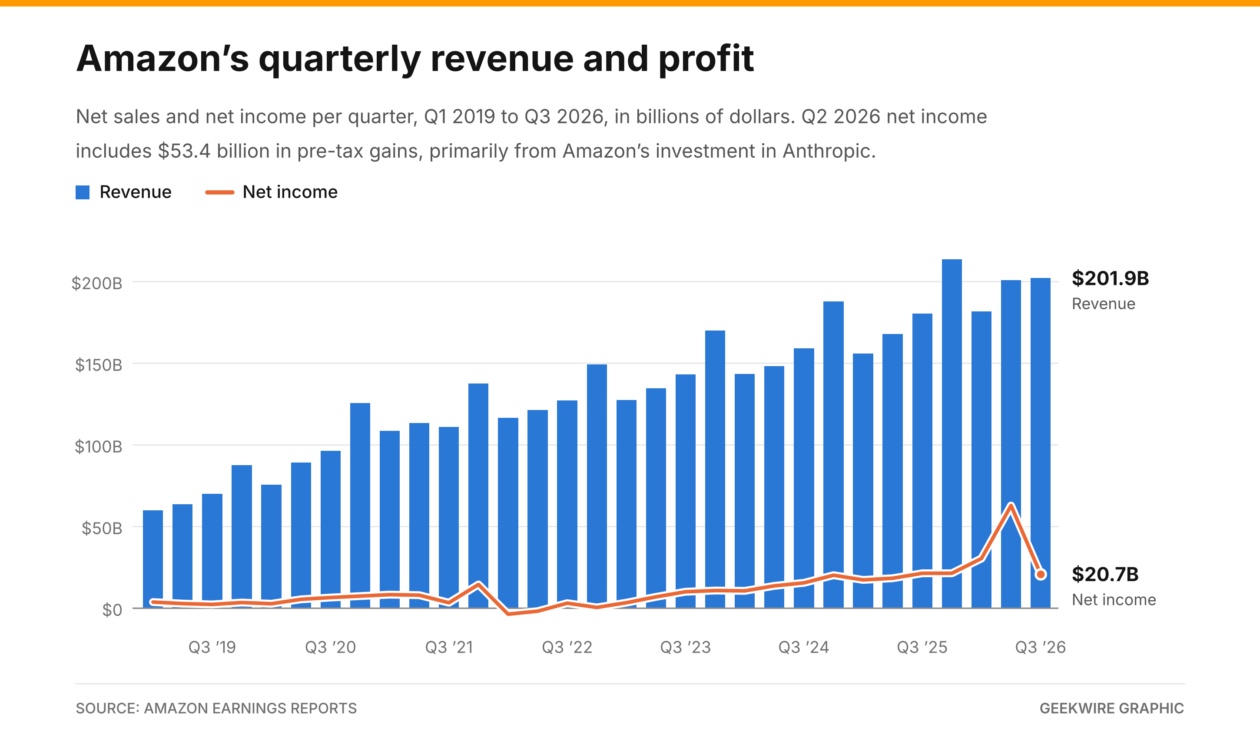
Outlook: Amazon expects fourth-quarter revenue of $240 billion to $247 billion, up 12% to 16%, and operating income of $28.5 billion to $33.5 billion.
Wall Street had expected fourth-quarter operating income of $33.2 billion, near the top of that range, according to analyst Dan Ives of Yorkville Ives. It still expects to spend about $220 billion on capital projects this year.
Amazon’s free cash flow, the cash left over after capital spending, was negative $42.4 billion over the past 12 months, compared with positive $14.8 billion a year earlier, mostly because of its AI investments.